Seller Concession vs. Price Reduction: Which Actually Saves the Buyer More?
Title: Seller Concession vs. Price Reduction: Which Actually Saves the Buyer More?
Meta description / subhead: A $10,000 price cut barely moves a buyer’s monthly payment. The same $10,000 as a seller-paid rate buydown can move it several times more in the first two years. A Grand Rapids broker explains the math — and the honest limits.
Quick answer
When a seller gives up $10,000, a price reduction lowers the buyer’s monthly payment by a small amount for the life of the loan. The same $10,000 as a seller concession funding a 2-1 temporary buydown lowers the payment several times more in year one, and still meaningfully in year two, with money left over for closing costs. The seller nets the same amount either way.
The price cut is permanent but small. The buydown is temporary but large. For most buyers who won’t keep the exact same loan for a decade or more without refinancing or selling, the buydown delivers more real relief. The details — and the honest limits — are below.
The situation this solves
A listing has been sitting. The seller is ready to move $10,000 to get it sold. Almost everyone reaches for the same tool: drop the price.
Meanwhile, the buyer on the other side isn’t stuck on the price — they’re stuck on the monthly payment. Those are different problems, and the price cut solves the wrong one.
A seller concession is money the seller agrees to credit the buyer at closing. It can pay closing costs, prepaid taxes and insurance, or — the part most people don’t know — fund a temporary interest rate buydown that lowers the buyer’s payment for the first year or two of the loan.
What a temporary buydown is
A temporary buydown pre-pays part of the buyer’s interest up front, so their payment is lower at the start of the loan. The two common versions:
- 1-0 buydown: the payment is calculated at a rate one point below the note rate for year one, then goes to the full note rate.
- 2-1 buydown: two points below in year one, one point below in year two, then the full note rate from year three on.
The money to fund it goes into an escrow account at closing and is drawn down each month to cover the difference. When a seller pays for it, it’s a seller concession like any other — just aimed at the payment instead of the closing table.
Why the two shapes are so different
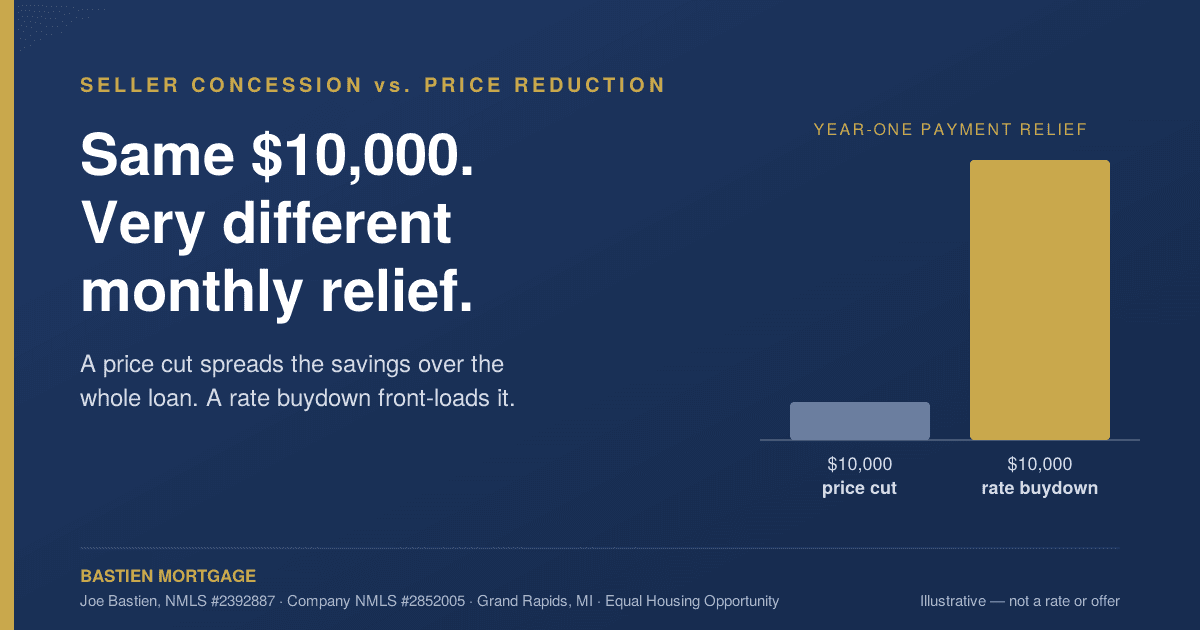
Spread $10,000 across a loan as a price reduction and it shrinks the balance by a little under 3% on a typical West Michigan purchase. That’s real, but spread over hundreds of payments it’s a modest monthly change.
Put the same $10,000 toward a 2-1 buydown and it’s concentrated into the first 24 payments instead of being spread across all of them. On a typical mid-priced purchase, year-one relief runs several hundred dollars a month — roughly six to seven times what the price cut delivers — and year two roughly three times. The buydown usually costs less than the full $10,000, so the remainder reduces the buyer’s cash to close.
Same seller, same dollars, different shape. One version saves the buyer a few hundred dollars in the first year. The other saves several thousand.
Side by side
| $10,000 price cut | $10,000 concession → 2-1 buydown | |
|---|---|---|
| Seller’s net proceeds | Same | Same |
| Sale price on record | Lower | Full price |
| Buyer’s monthly relief, year 1 | Modest, permanent | Several times larger |
| Buyer’s monthly relief, year 2 | Modest, permanent | Roughly half of year 1 |
| Buyer’s cash to close | Unchanged | Reduced by the unused remainder |
| When the price cut catches up | — | Roughly a decade, depending on rate |
The lighter version: a 1-0 buydown
If the seller offers less, or the buyer’s real constraint is cash rather than payment: a 1-0 buydown costs roughly a third of a 2-1, leaving most of a $10,000 concession for closing costs and prepaids. For a first-time buyer scraping together cash to close, this is often the better shape.
Why this matters to sellers and listing agents specifically
- The comp. A price reduction records a lower sale — which lowers comparable sales for every nearby listing, including the agent’s other ones. A concession keeps the recorded price intact.
- The stuck listing. “Seller will contribute toward a rate buydown” in the listing remarks reaches buyers who were scared off by payment math, without touching the price.
- The appraisal. A concession sits inside the contract price; a price cut is a lower number that can drag the next appraisal in the area.
- The offer that wins. A buyer who writes at full price with a concession request reads better to a seller than a lowball — and it can net the buyer more.
The honest trade-offs
This is a tool, not a trick. Here’s when it doesn’t win.
- It’s temporary. Years one and two get relief; year three the payment goes to the full note rate. The buyer has to plan for that — it’s the single most important thing to understand before choosing it.
- The buyer must qualify at the full note rate, not the bought-down rate. A buydown helps an approved buyer breathe easier. It does not help someone get approved.
- Long holds favor the price cut. Keep the identical loan for roughly a decade without refinancing or selling, and the permanent reduction eventually overtakes the buydown. Most people don’t — but it’s real.
- If the buyer sells or refinances early, the unused buydown funds are generally applied to the loan payoff. The money isn’t lost, but confirm the handling with your lender on each file.
- A buydown for a buyer planning to refinance within a year is a gift to nobody. In that case, a 1-0 or a straight closing-cost credit is smarter.
- Concessions have caps. Conventional loans: generally 3% of the price when the down payment is under 10%, 6% between 10% and 25%. FHA: 6%. VA: certain concessions capped at 4%. Anything above the cap is simply lost — so know the buyer’s loan type before the offer is written.
How it gets written into the deal
In the purchase agreement, concession language along these lines keeps the funds flexible and protects everyone:
“Seller to credit Buyer $[amount] toward closing costs, prepaids, and/or a temporary interest rate buydown, subject to lender approval and program limits.”
And the one call that prevents problems: before the offer is written, ask the lender two questions — “What’s the concession cap for this buyer’s loan?” and “What does a 2-1 cost on this price?” Sixty seconds. It prevents an over-cap concession, a buydown the program doesn’t allow, or a payment plan built on a rate the buyer was never going to qualify at.
Frequently asked questions
Does a seller concession cost the seller more than a price reduction? No. A $10,000 concession and a $10,000 price cut produce the same net proceeds for the seller. The difference is entirely in what the buyer receives.
Can seller concessions pay for a rate buydown? Yes — on most conventional, FHA, and VA purchase loans, seller-paid temporary buydowns are allowed, subject to the concession caps for that loan type and lender approval.
What’s the difference between a 1-0 and a 2-1 buydown? A 1-0 lowers the payment rate by one point for the first year only. A 2-1 lowers it by two points in year one and one point in year two. The 2-1 delivers more relief and costs roughly three times as much.
Does a temporary buydown help me qualify for a bigger loan? No. Lenders qualify you at the full note rate. A buydown lowers your early payments; it doesn’t change your approval.
Is a buydown better than a price reduction? Usually, for a payment-sensitive buyer who won’t hold the identical loan for a decade or more — but not always. A buyer who plans to refinance within a year, or whose main problem is cash to close rather than payment, may be better served by a different shape of the same dollars. That’s a conversation worth having before the offer is written.
Who do you work with in West Michigan? Buyers, sellers, and agents across Grand Rapids, Grandville, Wyoming, Kentwood, Rockford, Ada, Jenison, Caledonia, Holland, and the surrounding Kent, Ottawa, Allegan, and Barry county communities.
Agents and broker-owners: I’ve built this into a fifteen-minute walkthrough with worked numbers for sales meetings — I bring lunch and I don’t pitch from the front of the room. Buyers and sellers: if you want this math run on a real listing, call or email me and I’ll show you both shapes of the same dollars on your actual numbers.
Joe Bastien · Bastien Mortgage LLC · NMLS #2392887 · Company NMLS #2852005 · 616-369-0021 · joe@bastienmtg.com · bastienmortgagemi.com · 446 Hubbard St NE, Grand Rapids, MI 49525 · Equal Housing Opportunity
This article is educational and is not a loan offer, approval, or commitment to lend. Buydown availability, concession limits, and program eligibility vary by lender and loan type and are subject to underwriting approval. Program rules current as of October 2026 — verify before acting.